How Much Should My Emergency Fund Amount Be?
How Much Should My Emergency Fund Amount Be?
How AI can help you create an Emergency Fund and more
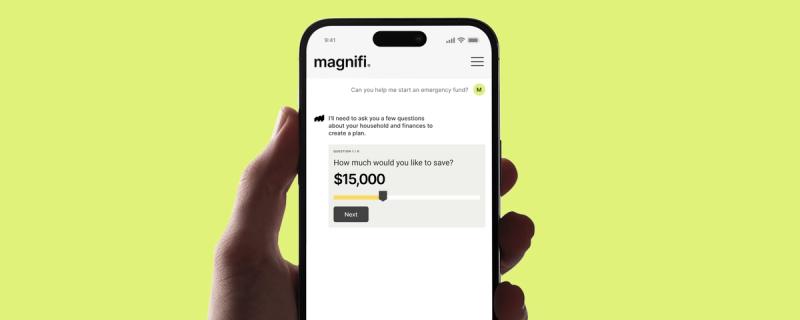
Whether you’re investing to accelerate your retirement, to buy a house, or just build up your rainy day fund, Magnifi can help. Magnifi is the world’s first AI designed to help you find, analyze, and buy investments, precisely for your unique financial goals.
You can make a plan, understand your likelihood of success, and start investing in minutes. Magnifi will even help you manage your investments and streamline your investing over time. Powered by conversational AI, now investing is as simple as texting.
[Click here](https://magnifi.com/magnifi-personal/payment-checkout?utm_medium=organic&utm_source=learnarticle&utm_campaign_id=learn&utm_ad_type=content&utm_goal=paidsub&utm_content=emergencyfund&utm_date=q223)
How Much Is My Emergency Fund Amount?
An emergency fund is essentially a financial safety net that individuals or households set aside in an effort to help cover unexpected expenses or income lapses. An emergency fund can act as a buffer to help mitigate financial hardships in case of these unforeseen events, and the funds can provide a sense of security in times of crisis. These funds are crucial for everyone, regardless of their income level or perceived financial stability. Emergencies do not discriminate; they can happen to anyone at any time.

As such, emergency fund examples are numerous and diverse, ranging from unexpected car repairs and medical bills to sudden job loss or natural disasters. Let’s consider a few scenarios to understand how setting aside an emergency fund amount can make a difference:
- Jane, a working professional, experiences a major car breakdown. To replace the parts and cover labor expenses, the mechanic quotes a $1,500 repair bill. Thankfully, however, Jane has an emergency fund of $2,000 set aside just in case. With this emergency fund, she can cover surprise expenses without having to turn to credit cards or taking out loans.
- Marcus, a self-employed business owner, encounters a downturn in his business and experiences a significant decrease in income for several months. Luckily, his emergency fund of $10,000 helps cover his living expenses until the business recovers, preventing him from falling into significant financial hardship.
The average emergency fund amount will vary greatly depending on individual circumstances, but financial experts typically recommend saving around three to six months’ worth of living expenses in a high-yield savings account (1). How much is enough likely depends on numerous contributing factors including expenses like housing, utilities, groceries, debt payments, insurance premiums, and others. By multiplying average monthly expenses by the desired number of months, one can reasonably estimate a decent target emergency fund amount.
Emergency Fund Calculators
Determining the appropriate size of an emergency fund necessitates a careful consideration of various factors including monthly expenses, income stability, and risk tolerance. There are different methodologies, formulas, and tools available to help individuals calculate their ideal emergency fund size.
So, how much should an emergency fund cover? Many financial experts recommend saving up enough to cover three to six months’ worth of living expenses. To calculate this figure, individuals need to estimate their average monthly expenses including all the essential items (housing, utilities, groceries, debt payments, and insurance premiums). Using a 6-month emergency fund calculator, determining the desired amount is relatively simple.
Using an emergency fund calculator is a quick and easy way to streamline the process. Many of these calculators have users input certain information related to monthly expenses, income, and desired number of months to cover. The calculator will then spit out a number based on the figures you feed it.

Additionally, some financial experts suggest using the emergency fund ratio formula (2). This formula is designed to help individuals save a percentage of their annual income to bolster their emergency fund. The exact percentage may vary somewhat, but using that commonly-cited range of three to six months, individuals can figure out their own amount relatively simply.
There’s also a wide variety of tools from money mentors like Dave Ramsey (3) that can aid in determining an emergency fund size. It considers factors like monthly expenses, relative income stability, and personal risk tolerance to offer more customized recommendations.
Savvy individuals will note, however, that these methodologies and tools are meant to provide only general guidelines; individual circumstances will likely warrant adjustments. Other factors like job security, health conditions, and financial obligations should also be taken into account when determining the appropriate size of your emergency fund.
How Much Should I Put in My Emergency Fund Per Month?
There are several questions that are important to consider throughout this process. Questions like “How much should I put in my emergency fund per month,” and “Which of these is a good reason to tap into your emergency fund,” can be helpful starting points, but how often should you review and adjust your emergency fund?
Here’s a brief guide to help you navigate the process:
- Establish the Fund – Start by setting a specific and achievable savings goal for your emergency fund. Aim to save enough to cover your living expenses for a minimum of three months. To begin, you might consider saving a small amount early on and gradually increasing it over time. You might also consider automating your savings by configuring automatic transfers to your emergency fund.
- Prioritize Consistency – They say consistency is key and that’s true here too. Develop the habit of contributing to your fund each month and treating it as a non-negotiable expense. Even if you can only save a small amount initially, the key is to make a continuous, concerted effort.
- Separate and Protect – Ensure that your emergency fund is insulated from your regular checking or savings accounts. This separation can help you distinguish between emergency funds and everyday spending, reducing the likelihood of using the emergency fund for non-emergency purposes.
- Using Your Emergency Funds – An emergency fund turns a crisis into an opportunity to handle unexpected expenses without taking on debt. It should be used for genuine emergencies only (job loss, medical emergencies, major vehicle repairs, home repairs, etc.). Evaluate the urgency, necessity, and impact of the expense before tapping into your emergency fund.
- Replenishing Emergency Funds – After using your emergency fund, make it a priority to replenish it as soon as feasibly possible. Then resume regular contributions until the fund is completely replenished.
By diligently building and managing your emergency fund, you can create a greater sense of financial confidence and readiness.

Emergency Fund vs Savings Accounts
Why do you think they recommend saving 3-6 months of expenses in your emergency fund? And how much is 3-6 months of expenses anyway? This amount will likely depend on each individual’s circumstances. However, the basic logic behind that mysterious three-to-six-month-long period is that the nature of emergencies is largely unknowable. A robust emergency fund can prevent people from emptying their savings and buy a little time to recover from the emergency.
Emergency funds are specifically designated to handle unexpected expenses and financial crises. They act as a financial safety net and provide relative stability during challenging times. Emergency funds should only ever be used to pay for unforeseen circumstances. The focus is on immediate accessibility and liquidity to address urgent needs without issue.
Savings accounts, on the other hand, are typically set aside as a general fund for various purposes and future expenses. Savings accounts are more commonly used to cover planned expenses and long-term objectives. General savings can be allocated towards short-term goals like vacations, down payments on a house, or purchasing a vehicle. They can also be utilized to help with long-term goals like retirement, education, or other investments.
Unlike emergency funds, general savings may have different levels of accessibility depending on the specific goal or purpose. Some savings may be kept in easily accessible accounts, while others may be invested in assets with varying degrees of liquidity. The size of general savings will vary depending on an individual’s financial goals and priorities and is also determined by factors like desired purchases, retirement plans, or other financial milestones.
Where to Keep Emergency Fund
So, now that you have a better idea of how much to set aside in this special kind of fund and what these emergency funds are used for, but how do you figure out where to keep these emergency fund accounts? Here are a couple key pieces of the puzzle to be aware of:
- Why might it be better to keep your emergency fund money in a separate account? – Keeping your emergency fund monies in a separate account is beneficial for a couple of reasons. Firstly, it helps maintain clear boundaries between your regular spending money and emergency funds. Secondly, having a dedicated account for emergency funds makes it easier to track and monitor the fund’s growth and availability.
- Why shouldn’t you keep your emergency fund money in your checking account? – Keeping your emergency fund money in your checking account may not be ideal because it could blur the distinction between your everyday expenses and emergency funds. It increases the risk of unintentional spending and reduces the visibility of the fund’s growth and availability. Additionally, a checking account typically offers minimal interest, resulting in the potential loss of long-term value and purchasing power due to factors like inflation.
When considering whether to keep an emergency fund in cash or invest, it’s important to assess your risk tolerance and financial goals to make an informed decision. Cash can provide immediate accessibility and stability during emergencies, but investing may offer potential growth and built-in inflation protection. Balancing the need for liquidity with the desire for long-term returns is essential. Ultimately, the decision should align with your individual circumstances, preferences, and goals to ensure an informed choice for effectively managing your emergency funds.
Try Magnifi Today
Ready to start investing? Click here to meet Magnifi today.
References:
- “What's the right emergency fund amount?”, investor.vanguard.com, https://investor.vanguard.com/investor-resources-education/emergency-fund
- “Emergency Fund Ratio Calculator”, November 14, 2022, Calculator Academy, https://calculator.academy/emergency-fund-ratio-calculator/
- “Tools and Resources”, ramseysolutions.com, https://www.ramseysolutions.com/tools?snid=free-tools
Disclosures:
Magnifi is changing the way we shop for investments, with the world’s first semantic search engine for finance that helps users discover, compare, and buy investment products such as ETFs, mutual funds, and stocks. Open a Magnifi investment account today.
The information and data are as of June 1, 2023, unless otherwise noted and subject to change. This blog is sponsored by Magnifi.
This material is provided for informational purposes only and should not be construed as individualized investment advice or an offer or solicitation to buy or sell securities tailored to your needs. This information covers investment and market activity, industry, or sector trends, or other broad-based economic or market conditions and should not be construed as investment research or advice. Investors are urged to consult with their financial advisors before buying or selling any securities. Although certain information has been obtained from sources believed to be reliable, we do not guarantee its accuracy, completeness, or fairness. Past performance is no guarantee of future results. This content may not be reproduced or distributed to any person in whole or in part without the prior written consent of Magnifi. As a technology company, Magnifi provides access to tools and will be compensated for providing such access. Magnifi does not provide broker-dealer or custodial services.